Compare Medical Equipment Finance & Loans from 50+ Australian Lenders
Acquire the medical equipment your practice needs without draining cash flow. Get real quotes in minutes with no impact on your credit score.

5.0 rating
Medical Equipment Finance Made Simple
Finance diagnostic machines, surgical tools, dental chairs and more. Flexible terms designed for Australian doctors, dentists, specialists, and healthcare providers.
Borrow With Confidence
Typical amounts from $5,000 to $500,000+
Flexible Terms
Loan terms from 1 to 7 years
Same-Day Approvals
Available for straightforward applications
Secured by Equipment
Keep rates low by securing against the asset
Tax Effective
Claim deductions on interest and depreciation
Any Healthcare Purpose
From imaging to IT systems and patient care
How Medical Equipment Finance Works
We connect you with specialist lenders that support healthcare providers, with equipment finance matched to the asset and the practice.
Apply online in minutes
Tell us about your practice and the equipment you need. It takes just a few minutes.
Get matched offers
Our Lender Match technology finds quotes from multiple lenders suited to healthcare businesses.
Choose your finance option
Compare interest rates, fees and repayment terms to select the right loan for your practice.
Get approved and settle
Same-day approvals are available for straightforward applications, and at settlement the funds are paid directly to the vendor or dealer.
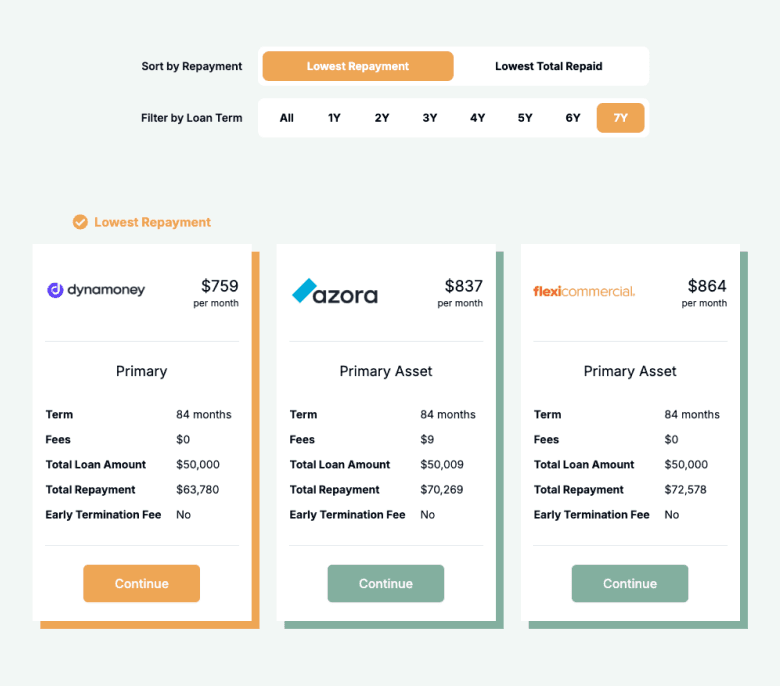
Backed by over 50+ lenders
Giving you the best chance of being approved.
A quick guide to medical equipment finance
Medical equipment finance helps healthcare providers access the technology they need without paying upfront. Instead of tying up capital, repayments are spread over time to preserve cash flow for wages, rent, and patient services. This page covers the equipment itself; the finance for medical professionals hub covers practice loans, fit-out, cars and personal borrowing for doctors, dentists and vets.
Loans are usually secured against the equipment, which allows lenders to offer lower rates and higher borrowing amounts than unsecured lending. Terms often range from 1 to 7 years, and repayments can be structured to align with practice revenue cycles.
Finance can be used across many medical fields: from diagnostic imaging and surgical tools to dental chairs, physiotherapy equipment, and even software like electronic health records or telemedicine platforms.
For doctors, dentists, specialists and clinics, medical equipment finance keeps the latest technology within reach, supports patient care and lets the practice grow without straining its cash flow.
Want to skip ahead?
This guide is broken down into the following sections. Click a link if you want to skip ahead.
Types of medical equipment finance
Here are the most common medical equipment finance options available in Australia:
Chattel Mortgage
A secured loan where you own the asset from day one while the lender holds a mortgage over it as security. Perfect for business equipment, vehicles, and machinery purchases.
Pros
- Immediate ownership of the asset
- Tax benefits - claim GST credits and depreciation
- Flexible repayment terms available
- Lower interest rates due to security
Cons
- Asset serves as security - risk of repossession
- Comprehensive insurance typically required
- Ongoing maintenance responsibilities
Best For
Established businesses looking to purchase equipment, vehicles, or machinery with immediate ownership and maximum tax benefits.
Finance Lease
A lease agreement where you use the asset throughout the lease term with the option to purchase it at the end. Ideal for businesses wanting to preserve cash flow while accessing essential equipment.
Pros
- Lower upfront costs and deposits
- Preserves working capital and credit lines
- Tax deductible lease payments
- Option to purchase at lease end
Cons
- No ownership until lease completion
- Total cost may be higher than outright purchase
- Early termination penalties may apply
Best For
Growing businesses that need equipment access without large capital outlay, or companies wanting to preserve cash flow for operations.
Hire Purchase
A financing arrangement where you hire the asset with an obligation to purchase it at the end of the term. Combines the benefits of gradual ownership with manageable monthly payments.
Pros
- Guaranteed ownership at term completion
- Fixed monthly payments for budgeting
- No large upfront capital required
- Tax benefits available during the term
Cons
- No ownership until final payment made
- Higher total cost than outright purchase
- Asset cannot be sold during the term
- Early termination may incur penalties
Best For
Businesses that want eventual ownership of assets but need to spread the cost over time, particularly suitable for essential equipment with long useful life.
What can I use medical equipment finance for?
Finance can be used across many healthcare needs:
Diagnostic Imaging
Acquire X-ray machines, CT scanners, ultrasound systems and other imaging technology.
Surgical Instruments
Purchase essential surgical tools and operating theatre equipment.
Monitoring Devices
Finance patient monitors, ECG machines and other testing equipment.
Dental Equipment
Finance dental chairs, X-ray machines, and specialist instruments.
Medical Furniture
Cover the cost of examination tables, patient beds and furnishings.
Physio & Rehab
Acquire rehabilitation and physiotherapy devices such as treadmills and therapeutic tools.
Laboratory Equipment
Finance microscopes, centrifuges and analysers for diagnostic testing.
Mobile Medical Units
Finance ambulances and mobile clinics to serve remote areas.
Optical & Ophthalmic
Invest in optometry and ophthalmic equipment such as phoropters and lens edgers.
Medical IT & Software
Support electronic health records, management systems and telehealth platforms.
Finance for practices: beyond the equipment
Equipment is one line in a practice budget, and the rest sits on different facilities. Medical practice loans cover buying into or buying a practice, start-up practice lending and working capital, and fit-out finance covers the rooms the equipment goes into, where items that become fixtures may require additional security.
The finance for medical professionals hub links the profession pages for doctors, dentists and vets, and two cost guides: how much an MRI machine costs and setting up a medical practice. Each of those pages points back here for the equipment finance figures and adds the practice-side detail.
Case Study
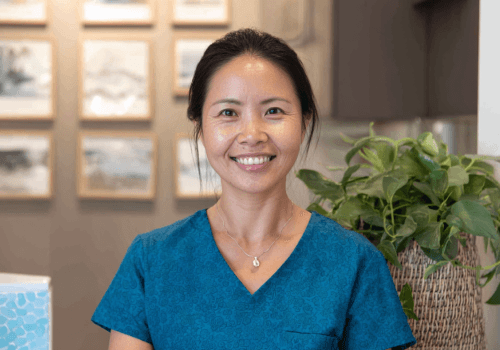
Dr. Emily Tran, Bright Smiles Dental
Improving Patient Care with Finance
Industry: Dental Practice
Challenge: Outdated dental equipment impacting patient experience and efficiency.
Solution: A 5-year chattel mortgage secured against new dental chairs and imaging tools.
Dr. Emily runs a busy dental clinic in Melbourne. Her outdated equipment meant longer procedures and patient discomfort. Through Emu Money, she secured finance for new dental chairs and a digital X-ray machine using a chattel mortgage. Repayments were structured over 5 years, keeping cash flow manageable while improving service quality. The new equipment enhanced diagnostic accuracy, reduced treatment times, and improved patient satisfaction, which lifted clinic growth and referrals.
How much can I borrow with medical equipment finance?
In Australia, medical equipment finance usually ranges from $5,000 for smaller devices up to $500,000+ for advanced diagnostic machines. The loan amount depends on the equipment’s purchase price, expected lifespan, and your practice’s financial position.
Because the loan is secured against the equipment, lenders are more willing to offer higher borrowing limits and better interest rates than unsecured loans.
Am I eligible for medical equipment finance?
Eligibility is generally straightforward as equipment is considered an income-generating asset. Lenders assess your credit profile, turnover, and practice history.
You may be eligible if you are:
An Australian citizen or permanent resident
Over 18 years old
Running a registered medical, dental, or healthcare practice
Able to provide recent financials or bank statements
Hold an ABN (and GST registration if required)
How to apply for medical equipment finance
Complete a quick online application to see instant quotes from multiple lenders. Select your preferred option and submit documents; same-day approvals are available for straightforward applications.
Documents you may need:
ABN and GST registration details
Photo ID (passport or driver’s licence)
Recent practice bank statements
Tax returns or financials (for larger loans)
How to save money on medical equipment finance
To save money, compare offers across multiple lenders as interest rates and fees vary widely. Choosing a shorter term reduces overall interest costs, though repayments are higher. Longer terms ease cash flow but increase total costs.
Check for hidden costs like establishment fees or early repayment penalties. If your practice has stable revenue, making additional repayments or paying off early can reduce interest expenses.
Finally, align repayment frequency with your patient billing cycles (weekly, fortnightly, monthly) to avoid stress and late payment fees.
Example: $100,000 financed at 7.95% p.a.:
| Term | Repayment Amount | Total Amount to Repay |
|---|---|---|
24 months | $4,519 | $108,463 |
36 months | $3,132 | $112,771 |
48 months | $2,454 | $117,790 |
60 months | $2,015 | $120,916 |
Understanding medical equipment finance options
Medical equipment finance comes in many forms, and understanding how they work can help you choose with confidence:
Security: Asset-backed
Most loans are secured by the equipment itself, giving lenders confidence and lowering interest rates compared to unsecured products.
Personal Guarantee
Some lenders require a personal guarantee from the doctor, dentist, or director, making you personally responsible if repayments aren’t met.
Term: Fixed vs Revolving
Most medical finance is offered as fixed-term loans (1 to 7 years). Some leases allow ongoing use with end-of-term options.
Interest Structure
Fixed rates are common, giving predictable repayments. Variable rates exist but are less common in healthcare lending.
Fees & Charges
Check for establishment fees, ongoing charges, and early termination costs. These can vary significantly between lenders.
Repayment Frequency
Choose weekly, fortnightly, or monthly repayments. Aligning with your billing cycle (e.g., Medicare payments) helps manage cash flow.
Estimate your equipment finance repayments
See what your repayments would look like before you apply. Enter a loan amount, term, and rate to get an instant estimate with a full amortisation schedule.
- Compare finance structures
- Full amortisation schedule
- Instant results, no sign-up
- Adjustable rates and terms
Guides for medical practices
The practice-side pages that sit behind an equipment purchase.
Finance for Medical Professionals
The section hub: practice, equipment, fit-out, car and working capital finance for doctors, dentists and vets.
Medical Practice Loans
Buying into or buying a practice, start-up practice lending, working capital and premises.
Medical and Dental Fit-out Finance
What a fit-out facility covers, how draw-down facilities work and how the tax treatment differs from equipment.
How Much Does an MRI Machine Cost?
New and refurbished prices by field strength, site works, running costs, Medicare rules and finance.
Finance for Dentists
Dental practice loans, chairs and CBCT finance, and buying into a practice.
Setting Up a Medical Practice: Checklist and Costs
Registration, provider numbers, premises, fit-out, equipment, staff and the finance behind each step.
Testimonials
See what our customers have to say about us.
Verified Review
Thanks for all your help and dedication, it was super fast and easy to get my vehicle load approved and they found my vehicle in less then a day. smooth ans swift thanks Peter!
Barend B.
Verified Review
What an amazing experience I had with Baron from Emu Money. He provided efficient and reliable advice and services.
Kayla H.
Verified Review
Very humble and respectful
Kazim A.
Verified Review
Sham S.
Verified Review
I've got the best service at Emu Money and their willingness to help you out. Evette went out of her way to help assist for the desired results. I will highly recommend them to anyone. Evette's industry knowledge & service was exceptional! I highly recommend her & will definitely reach out should we need any financial services in the future. Thank you
Mazhar A.
Verified Review
Just the best organiser and extremely helpful 👌. Strongly recommend!!!
Cleo C.
Frequently Asked Questions
Medical Equipment Finance FAQs
These helpful FAQs will help you find the answers you need. If you can't find what you're looking for, you can request a callback below.